
For each service provided or product sold domestically, VAT needs to be paid. This tax is borne by the end consumer, i.e. the German citizens, amounting to some €250 billion in 2021. Different tax rates and exceptions lead to a considerable lack of transparency and rising subsidies, and provide incentives for tax fraud.
VAT: Reform long overdue
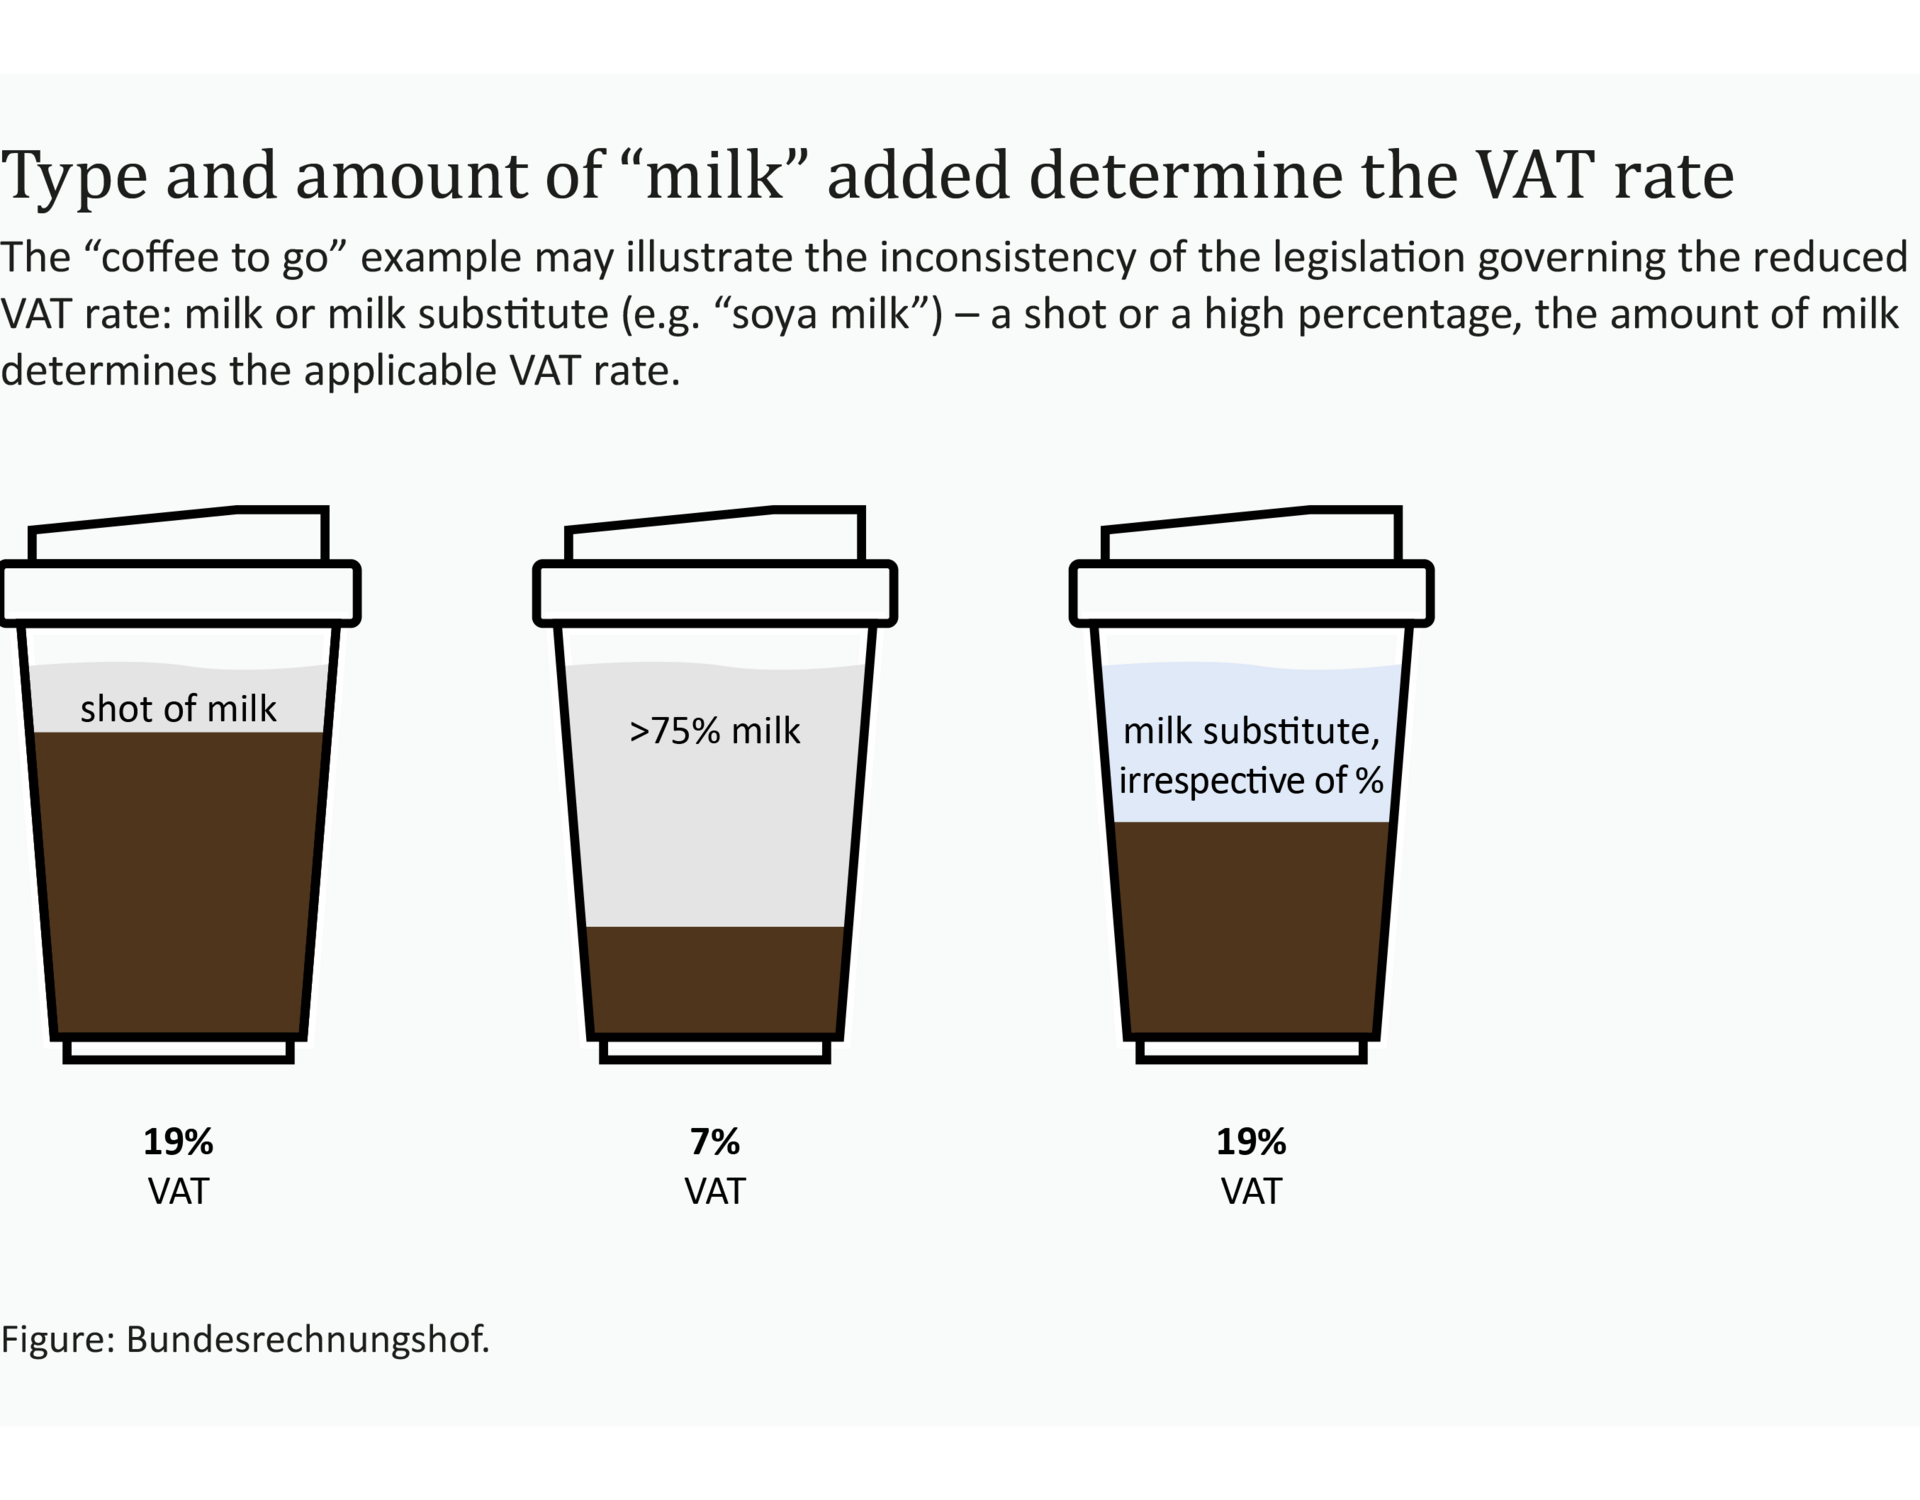
The list of exceptions allowing the application of the reduced tax rate continuously gets longer. Swimming baths, combustibles, lodging, transport – hardly any category is taxed at a consistent rate. Legislation is complex. It often leads to inconsistent results and considerable problems in making distinctions. For many years, VAT legislation has been dealt with by national and European courts.
In 2022, four sales categories that are taxed at a reduced rate counted among the 10 largest tax privileges:
- Restaurant and catering services (excluding beverage) – €3.1 billion;
- Cultural services – €3 billion;
- Public transport services – €1.9 billion; and
- Lodging services – €1.4 billion.
The VAT relief at a reduced rate almost amounts to an annualised €35 billion.
Each enterprise has the right to decide as to whether it passes on the tax advantage to the end consumer. It is therefore uncertain whether end consumers benefit from the tax relief. The Federal Government ultimately supports certain industry sectors at the expense of the public.
For that reason, we have urged the Government since 2010 to radically reform the VAT system. So far, however, the Government has failed to show the political will for change.
The time for a VAT reform is now
The EU adopted a directive applicable to all member states on the realignment of the VAT system. In this context, we urge the Government to thoroughly review the exceptions with the aim of introducing a simple and transparent VAT system. Tax privileges that lack transparency and unjustified subsidies need to be abolished. The use of tax privileges should be limited to basic services, and political patronage at the expense of the public should be avoided.
Downloads
Advisory report (Short info in English, long version only available in German)